Deferred interest in one sentence
With deferred interest, no interest is charged during the promotion only if you pay the entire balance by the deadline; if you do not, interest that built up in the background since day one can be added to your account.
What PatientFi says about its 0% plans
PatientFi offers zero-interest plans to approved applicants. Its disclosures state that zero interest applies when the balance is paid in full during the promotional period, and that these plans require enrollment in recurring payments. Its help center refers to “0% if paid in full” loans as deferred-interest promotional loans, and explains that their due dates are fixed by the contract.
Watch for this error on other sites
At least one PatientFi guide ranking in search describes the 0% promotion as “no deferred interest.” That conflicts with PatientFi’s own help center. If a source tells you a PatientFi 0% plan has no catch, check your actual loan agreement before relying on it.
A worked example
Say you finance a $6,000 procedure on a 12-month “0% if paid in full” plan, and the APR in your agreement for the deferred balance is 24.99%. (That rate is an example only. Your agreement shows your real rate.)
| Scenario | Monthly payment | Left at month 12 | Interest charged |
|---|---|---|---|
| Pay $500 a month | $500 | $0 | $0 |
| Pay $450 a month | $450 | $600 | About $881 |
| Pay $400 a month | $400 | $1,200 | About $950 |
Estimated interest is calculated on the declining monthly balance at 24.99% APR. Notice that being $600 short costs almost as much as being $1,200 short, because the interest is based on the whole history of the loan, not on what is left. Try your own numbers in the PatientFi calculator.
See deferred interest on a chart
Move the payment slider to see how close a small shortfall comes to a large interest charge. The APR is an example; use the one in your agreement. PatientFi lists APRs from 6.99% to 32.99%.
Why this matters: what the CFPB found
In its 2023 report on medical credit cards and financing plans, the Consumer Financial Protection Bureau found that patients paid about $1 billion in deferred interest on healthcare purchases between 2018 and 2020. Borrowers who were charged interest paid about 23% more than their original bill. Patients with credit scores below 619 were charged deferred interest on roughly 34% of purchases, compared with about 20% overall.
The CFPB also noted that these products are usually offered by the provider at the point of care, when patients may not fully understand the terms. That is exactly how PatientFi is offered, so read the offer screen slowly.
How to avoid PatientFi deferred interest
Calculate the real payment
Divide the balance by the number of promotional months, then round up. Pay that amount or more, even if the required minimum is lower.
Aim to finish one month early
Payments can take days to post. Planning to finish a month before the deadline protects you from a late posting.
Check autopay after every change
Several PatientFi complaints involve autopay not drawing a payment. Confirm the first payment posts, and check again if you change banks or cards.
Track each loan separately
Every new charge opens a separate PatientFi loan with its own deadline. Two procedures means two deadlines.
Pick fixed-rate if you are unsure
If there is a real chance you cannot clear the balance in time, a fixed-rate plan costs more up front but removes the risk of a large back-interest charge.
Printable checklist: before you sign a 0% plan
Print it, save it to your phone, or share it with someone about to finance a procedure.
PatientFiLoan
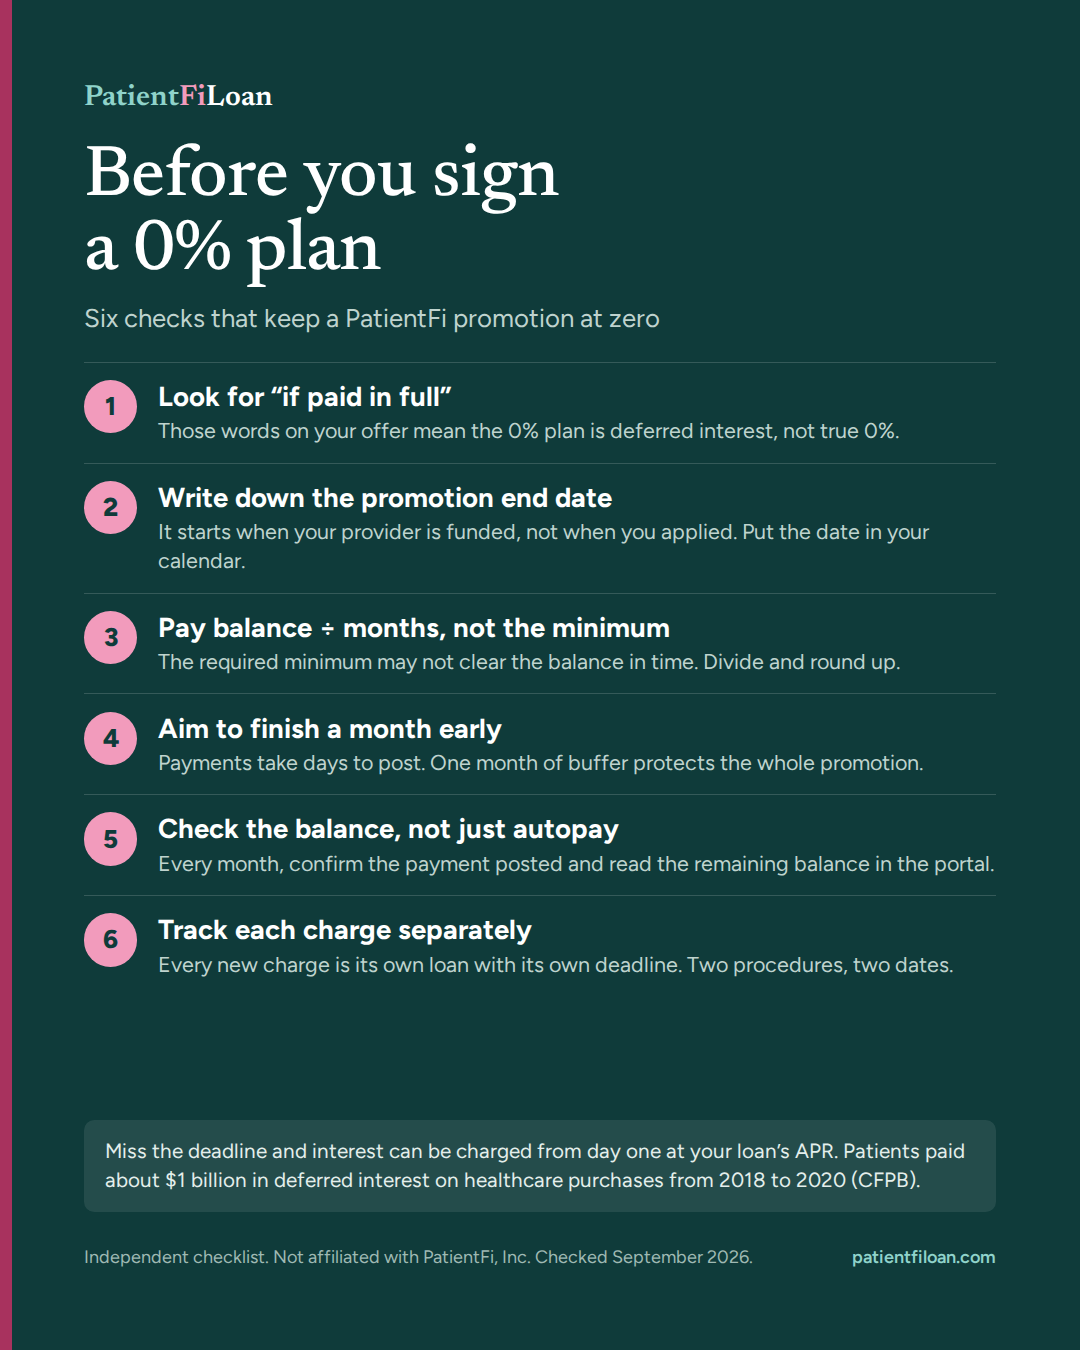
Before you sign a 0% plan
Six checks that keep a PatientFi promotion at zero
- Look for “if paid in full”Those words on your offer mean the 0% plan is deferred interest, not true 0%.
- Write down the promotion end dateIt starts when your provider is funded, not when you applied. Put the date in your calendar.
- Pay balance ÷ months, not the minimumThe required minimum may not clear the balance in time. Divide and round up.
- Aim to finish a month earlyPayments take days to post. One month of buffer protects the whole promotion.
- Check the balance, not just autopayEvery month, confirm the payment posted and read the remaining balance in the portal.
- Track each charge separatelyEvery new charge is its own loan with its own deadline. Two procedures, two dates.
Miss the deadline and interest can be charged from day one at your loan’s APR. Patients paid about $1 billion in deferred interest on healthcare purchases from 2018 to 2020 (CFPB).
Frequently asked questions
Does PatientFi charge deferred interest?
Yes, on its “0% if paid in full” promotional loans. PatientFi’s help center uses the term deferred interest for these plans. Fixed-rate PatientFi plans charge interest from the start instead and do not have a deferred-interest balloon.
If I have $50 left at the end of a PatientFi promotion, what happens?
On a deferred-interest plan, the remaining balance being small does not matter. Interest can be calculated on the balance from the original purchase date, not just on the $50. Check your loan agreement for the exact method.
Can I change the due date on a PatientFi 0% loan?
No. PatientFi says the due date on “0% if paid in full” promotional loans is set by the original contract and cannot be changed. Fixed-rate loans allow one due-date change over the life of the loan.
Does paying early help on a PatientFi 0% plan?
Yes. There is no prepayment penalty, and paying extra is the simplest way to guarantee the balance is gone before the promotion ends.